Written by
Reviewed by William Cooper
Follow us
Owning a country house often means looking after far more than the main building. Listed features, outbuildings, valuable possessions and changing lifestyles can all affect the cover you need.
We arrange insurance for a country house by understanding the property as a whole first: how it’s built, the prized possessions within it and what restoring everything after a serious loss could involve.
Specialist insurance for country houses
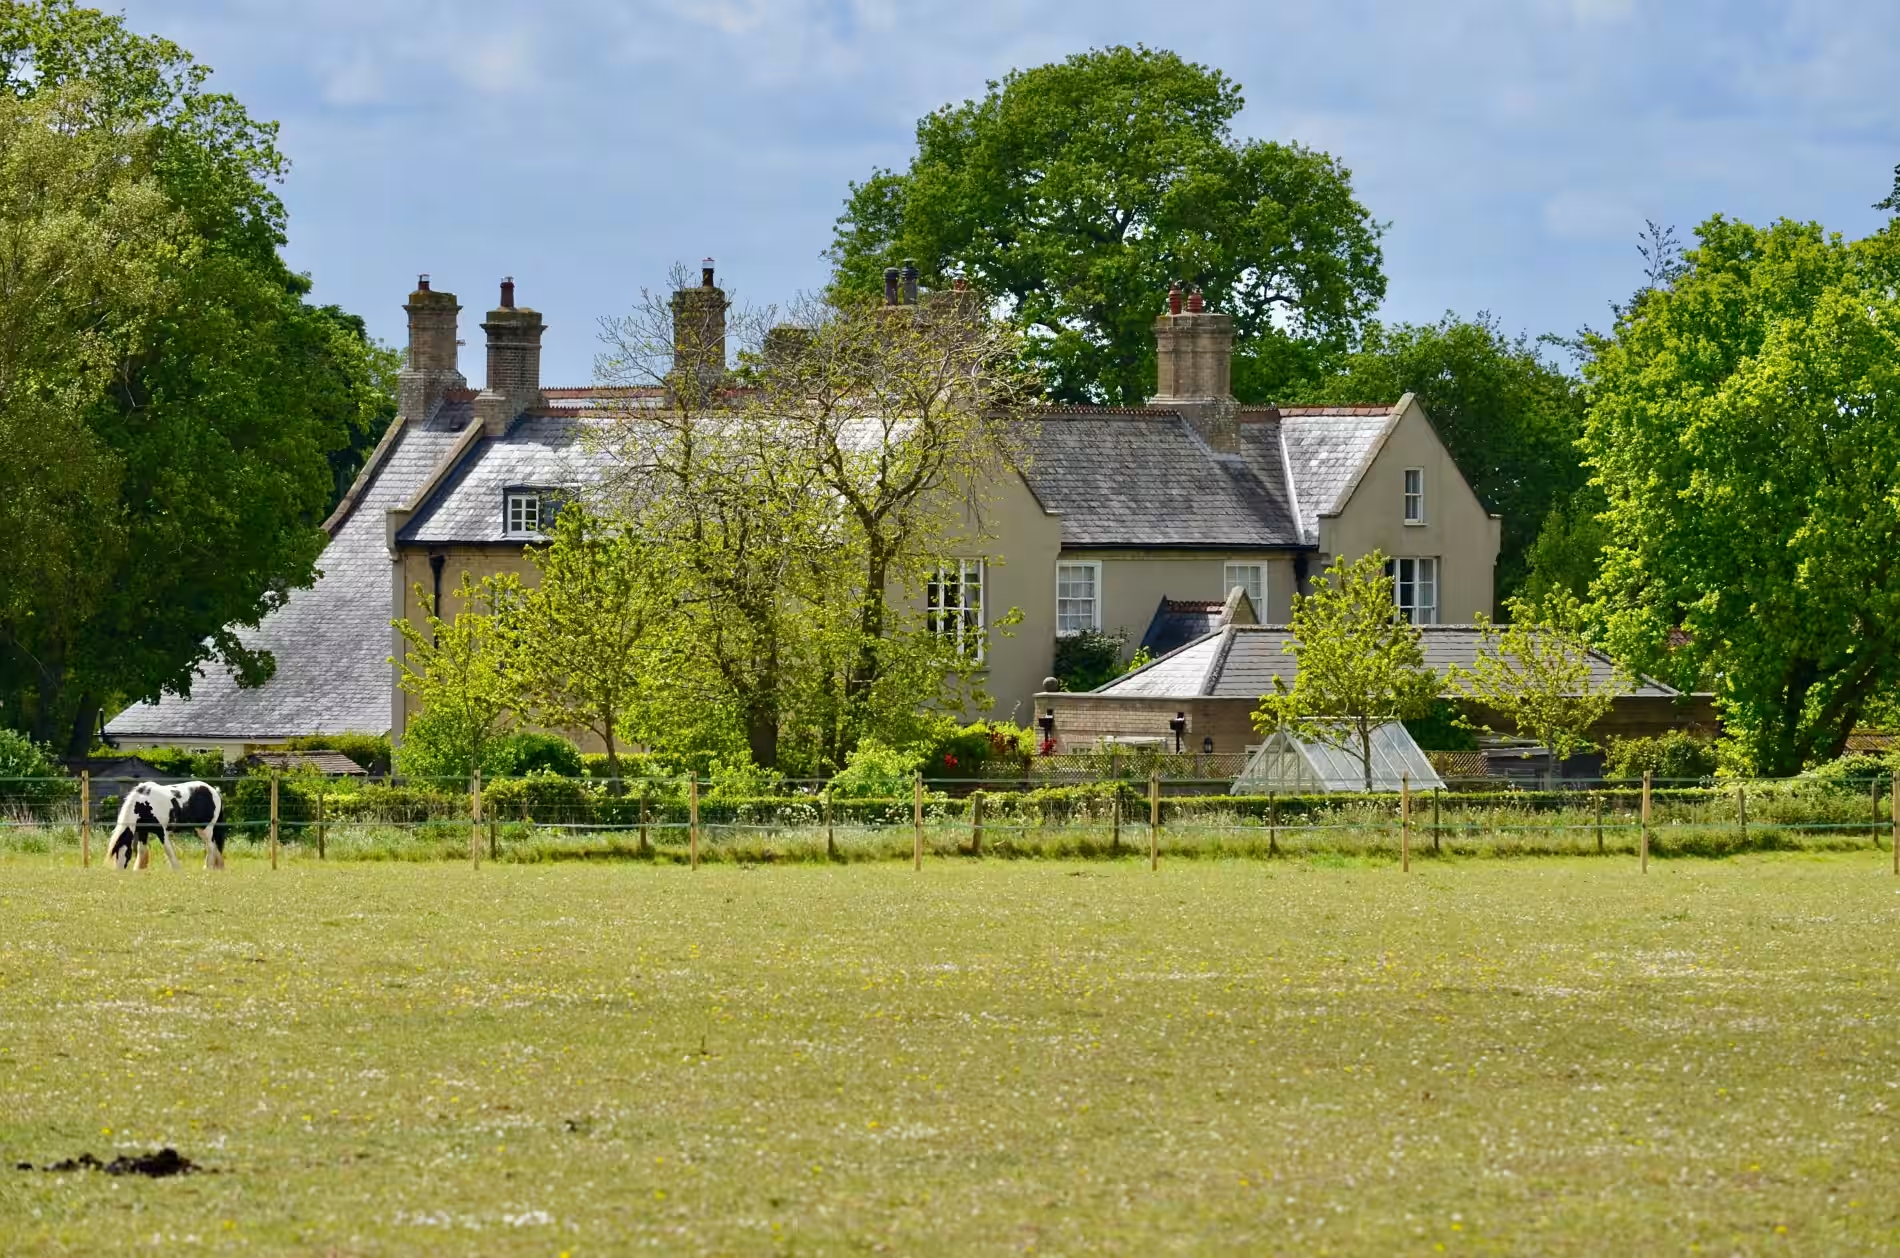
No two country houses are the same. One might be a listed family home with original features and several outbuildings. Another may have undergone extensive renovation or contain art, antiques and jewellery collected over many years.
While standard home insurance can be suitable for some properties, there are some situations where tailored high-value home insurance may provide a better fit, including:
- Where rebuilding is less straightforward
- Where valuable possessions require higher or more flexible limits
- Where the wider property includes several buildings that need to be covered under the same policy.
One of the first things we want to understand is what makes your home different. That gives us a clearer picture of what needs protecting before we start considering the policy.
What can country house insurance cover?
Depending on the policy and your circumstances, cover can include:
● The main house and other buildings on the property
● General household contents
● Art, antiques and other collections
● Jewellery and watches
● Possessions away from the home
● Cover across multiple properties
● Alternative accommodation following an insured loss
Our bespoke cover offers greater flexibility when conventional home insurance doesn’t reflect your circumstances.
Cover that reflects your country house
Many changes to a country house happen gradually, making it easy to overlook their impact on your insurance.
You might restore original rooms, build an extension or convert a barn. A collection can grow quietly over decades. Jewellery can be inherited. Artwork can move between properties.
Your rebuild value can change too. The rebuild value is the estimated cost of reconstructing your home after a serious insured loss. It isn’t the same as its market value. For period and listed properties, specialist materials, skilled craftspeople and conservation requirements can significantly increase rebuilding costs over time, making regular reviews essential.
Country houses are rarely just the main building
Barns, garages, cottages and other outbuildings are part of many country properties. But how they’re used can matter just as much as the buildings themselves.
A barn used for storage may need different insurance from one converted into an office, gym or guest accommodation. The same applies if any part of the property is used for letting, business activity, events or public access.
Tell us how the whole property works in practice. This helps us identify which buildings and activities need closer consideration rather than assuming everything is automatically treated in the same way.
Art, antiques, jewellery and watches can need additional attention, particularly where values have changed, collections have grown or possessions regularly move between homes or travel with you.
Where appropriate, we can also include cover for art, collections, jewellery and watches.
Speaking to a specialist broker isn’t about making insurance feel more complicated. It’s about recognising where a simple answer could leave too much unexplored. That doesn’t mean we’ll always recommend a different policy. Your existing insurance may still be the right choice.
Will Cooper, Managing Director, Stanhope
Get a country house insurance quote
You don’t need to know every answer before speaking to us. We’ll help you work through the important details and if your circumstances call for specialist cover, we’ll help you find an appropriate solution. If they don’t, we’ll tell you that too.
Talk to Stanhope about your insuring your country home.